Home Loan Calculator — EMI, Interest & Eligibility Calculator | AliGreat.com
Free Home Loan Calculator for India — calculate your home loan EMI, total interest, and check your FOIR eligibility against your monthly income.
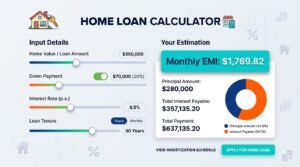
A home loan is likely the largest financial commitment most people ever make, often stretching 15 to 30 years and shaping monthly budgets for decades. Beyond just knowing the EMI, a smart borrower needs to know whether that EMI is actually affordable relative to their income — which is exactly what the Home Loan Calculator on AliGreat.com checks, alongside the standard EMI and interest numbers every loan calculator provides.
What does the Home Loan Calculator do?
Enter your loan amount, interest rate, tenure, and your monthly take-home income. The calculator shows your monthly EMI, total interest over the loan term, total amount payable, and — uniquely among the basic loan calculators — your FOIR (Fixed Obligation to Income Ratio), which tells you what percentage of your income the EMI alone will consume.
The formula behind it
The EMI itself uses the standard formula shared with every EMI-based loan: EMI = P × r × (1 + r)ⁿ / [(1 + r)ⁿ − 1], where P is the loan principal, r is the monthly interest rate, and n is the number of months. The eligibility check layered on top is simpler but just as important:
FOIR = EMI ÷ Monthly take-home income
A worked example
Suppose you take a home loan of ₹50,00,000 at 8.5% for 20 years, and your monthly take-home income is ₹1,20,000.
- r = 8.5 ÷ 12 ÷ 100 ≈ 0.007083
- n = 240 months
- EMI ≈ ₹43,391
- Total interest over 20 years ≈ ₹54,13,840
- Total payable ≈ ₹1,04,13,840
- FOIR = 43,391 ÷ 1,20,000 ≈ 36.2%
At just over 36%, this EMI sits comfortably within the typical 40-50% FOIR range most lenders use as an approval threshold, suggesting reasonable affordability relative to income. Now compare the same loan taken over 15 years instead of 20: the EMI rises to roughly ₹49,240, pushing FOIR up to about 41% — still generally within lender norms, but noticeably tighter, and total interest paid drops significantly to around ₹38,63,200, illustrating the classic trade-off between shorter tenure (higher EMI, lower interest cost) and longer tenure (lower EMI, higher total interest cost).
Why FOIR matters more than the EMI number alone
Two borrowers can have identical home loan EMIs but very different levels of financial comfort depending entirely on their income. A ₹43,000 EMI is comfortably manageable on a ₹1.5 lakh monthly income but genuinely tight on an ₹80,000 monthly income. Banks use FOIR (sometimes alongside other, more detailed debt-to-income ratios that also factor in existing loans and credit card obligations) precisely because the EMI figure alone doesn’t tell the whole affordability story — this calculator brings that same lens to your own personal planning, before you even approach a lender for pre-approval.
How lenders actually calculate eligibility (and where this calculator simplifies)
Real-world home loan eligibility assessments by banks typically go further than a single FOIR check on the proposed loan alone — they consider your total existing EMI obligations (car loans, personal loans, credit card minimum payments) as a combined percentage of income, along with your credit score, employment stability, co-applicant income if applicable, and the specific bank’s internal risk policies. This calculator’s FOIR check uses only the proposed home loan’s EMI against your income, giving you a useful directional signal, but your actual bank-assessed eligibility may differ once your full existing debt profile and credit history are factored in by the lender’s underwriting process.
Tax benefits on home loan interest and principal
Under the old tax regime, interest paid on a home loan for a self-occupied property can be deducted up to ₹2 lakh per year under Section 24(b) of the Income Tax Act, and principal repayment can qualify for deduction under Section 80C, within the overall combined ₹1.5 lakh 80C limit shared with other instruments like PPF and ELSS. For a let-out (rented) property, there’s no upper cap on the interest deduction under Section 24(b), though the overall loss from house property that can be set off against other income in a year is capped by current tax rules.
These deductions are not available at all under the new tax regime, which is an important factor to weigh when comparing the two regimes for someone who has just taken, or is planning, a substantial home loan — the potential tax savings under the old regime, especially in the early loan years when interest payments are highest, can meaningfully shift the old-vs-new regime comparison in the old regime’s favour for many home loan borrowers. AliGreat.com’s Salary Calculator lets you directly compare your in-hand income under both regimes, factoring in exactly this kind of deduction.
Budgeting beyond the EMI — costs this calculator doesn’t include
Stamp duty and registration charges typically add another 5-8% of the property value in most Indian states, on top of the loan amount itself — a cost that’s easy to overlook when focused purely on the monthly EMI. This is usually payable upfront in cash rather than financed as part of the home loan, so it needs to be budgeted separately, alongside costs like brokerage, home insurance, interior work, and moving expenses, none of which are captured by an EMI calculation alone.
A longer tenure isn’t always the “cheaper” choice
Stretching a loan from 15 to 25 or even 30 years lowers your monthly EMI and can meaningfully improve your FOIR-based eligibility, but it significantly increases the total interest paid over the life of the loan, as illustrated in the worked example above. Use this calculator to compare a couple of different tenure options side by side for the same loan amount — the EMI relief from a longer tenure often comes at a considerably higher total cost than it first appears when only looking at the monthly figure.
Loan-to-value ratio and down payment considerations
Indian banks typically finance up to 75-90% of a property’s value (depending on the loan amount slab), meaning you’ll need a down payment covering the remaining 10-25% from your own funds. A larger down payment directly reduces your loan principal, which in turn reduces both your EMI and your total interest paid — running this calculator with a couple of different loan amounts (reflecting different down payment sizes) against the same property value can help you decide how much to put down versus finance, especially if you have the flexibility to choose.
Balance transfer — refinancing an existing home loan
If interest rates have fallen significantly since you took your original home loan, or if a competing bank offers a meaningfully lower rate, a balance transfer (refinancing your outstanding loan to a new lender) can reduce your EMI or shorten your remaining tenure. Before committing to a balance transfer, use this calculator with your current outstanding balance, remaining tenure, and the new proposed rate to estimate the potential savings, and weigh that against the processing fees and other charges typically associated with a balance transfer.
Who should use this calculator
Anyone actively shopping for a home loan, comparing offers from different banks side by side, or simply trying to understand what loan amount and tenure combination fits comfortably within their income should run their numbers here before signing any loan agreement. It’s equally useful for existing home loan borrowers considering a balance transfer, or evaluating whether a lump-sum prepayment (covered separately in AliGreat.com’s Prepayment Calculator) makes more financial sense than continuing the current schedule.
Frequently asked questions
What FOIR percentage do banks typically consider safe for home loan approval? Most Indian banks look for a FOIR of 40-50% or lower on the proposed EMI relative to take-home income, though this threshold and the exact calculation method varies by lender and by the borrower’s overall income level and credit profile.
Do home loan tax benefits apply under the new tax regime? No — the Section 24(b) interest deduction and Section 80C principal deduction on home loans are available only under the old tax regime, not the new one.
Should I choose a longer tenure to reduce my EMI, or a shorter one to save on interest? This depends on your priorities — a longer tenure eases monthly cash flow and can improve loan eligibility, while a shorter tenure meaningfully reduces total interest paid; many borrowers choose a longer tenure initially for eligibility and cash flow, then use periodic prepayments to reduce the effective tenure over time.
Does this calculator include stamp duty and registration charges? No — it calculates only the EMI, interest and eligibility based on the loan itself. Stamp duty, registration, and other upfront property-purchase costs need to be budgeted separately, on top of the down payment.
Try it now
Open the Home Loan Calculator on AliGreat.com and check your EMI, total interest, and income-based eligibility — free, instant, and transparent about the formula used.