PPF Calculator — Public Provident Fund Maturity Value Calculator | AliGreat.com
Free PPF Calculator for India — calculate your Public Provident Fund maturity value, total deposits and tax-free interest over 15 years or more.
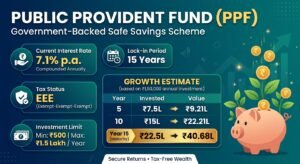
The Public Provident Fund remains one of the most trusted long-term savings instruments in India — backed directly by the Government of India, offering completely tax-free interest, and requiring no market knowledge whatsoever to use well. But because it locks your money in for 15 years with yearly deposits, most people open a PPF account without a clear picture of what it will actually be worth at maturity. The PPF Calculator on AliGreat.com fixes that with an instant, formula-based projection.
What does the PPF Calculator do?
Enter your yearly deposit amount (capped at the statutory limit of ₹1.5 lakh), the current interest rate, and your tenure — a minimum of 15 years, extendable afterward in blocks of 5 years. The calculator instantly shows your maturity value, total amount deposited over the tenure, and the tax-free interest earned on top of your contributions.
The formula behind it
PPF uses annual compounding, with deposits treated as made at the start of each financial year for calculation purposes:
FV = D × [((1 + r)ⁿ − 1) / r] × (1 + r)
where D is your yearly deposit, r is the annual interest rate (as a decimal), and n is the number of years. The government resets the PPF interest rate quarterly based on prevailing government bond yields, and it has typically sat around 7–8% in recent years — the calculator lets you adjust this rate as needed, so your projection stays current even as official rates change.
A worked example
Suppose you deposit the maximum ₹1,50,000 every year for the standard 15-year tenure, at a 7.1% interest rate.
- Total deposited over 15 years = ₹1,50,000 × 15 = ₹22,50,000
- Projected maturity value ≈ ₹40,68,000
- Interest earned (entirely tax-free) ≈ ₹18,18,000
Now extend the same yearly deposit for an additional 5-year block (20 years total, as PPF allows extension): the maturity value grows to roughly ₹62,60,000 — the additional 5 years alone contribute nearly as much growth as several of the earlier years combined, illustrating just how much compounding accelerates in the later years of a long-tenure account.
Why PPF is called “EEE”
PPF enjoys Exempt-Exempt-Exempt tax status, one of the most favourable tax treatments available on any Indian savings instrument. Your yearly contribution qualifies for a deduction under Section 80C (within the overall ₹1.5 lakh combined limit across all 80C instruments), the interest earned every year is completely tax-free with no upper limit, and the final maturity amount withdrawn after 15 years is also entirely tax-free. This triple exemption is genuinely rare — even instruments like NPS, which offer strong tax deductions on contribution, tax a portion of the eventual annuity income, whereas PPF taxes nothing at any stage.
The ₹1.5 lakh cap — and what happens if you cross it
Interest is calculated and credited only on deposits up to ₹1.5 lakh in a financial year — any amount deposited above this statutory cap earns no interest whatsoever, and is typically returned to the depositor without any interest attached, or held without earning until adjustable. The AliGreat.com calculator automatically flags this if you enter a figure above ₹1.5 lakh, since it’s a detail many account holders miss when trying to maximise contributions near the end of a financial year, particularly if depositing from multiple sources or accounts.
PPF interest calculation timing — a detail worth knowing
PPF interest is calculated monthly based on the lowest balance in your account between the 5th and the last day of each month, but is credited to your account only once a year, at the end of the financial year. This is why financial advisors commonly suggest depositing your PPF contribution before the 5th of April (the start of the financial year) if depositing as a lump sum, rather than later in the year — doing so ensures that full year’s deposit earns interest for the entire 12 months rather than a partial period.
Partial withdrawals and loans against PPF
PPF allows partial withdrawals starting from the 7th financial year of the account (from the year following completion of 6 years), subject to specified withdrawal limits based on the account balance. Loans against the PPF balance are permitted between the 3rd and 6th financial years, at a modest interest rate, offering some liquidity despite the account’s long headline lock-in. Beyond these structured options, PPF is generally treated by account holders as a purely long-term instrument rather than a source of emergency funds, given the withdrawal restrictions in the earlier years.
Extending your PPF account after 15 years
At the end of the initial 15-year tenure, you have three choices: withdraw the entire maturity amount and close the account, extend the account for further blocks of 5 years while continuing to make yearly deposits, or extend the account without making further deposits, letting the existing balance continue earning interest. Each of these paths has different implications for liquidity and growth, and the AliGreat.com calculator lets you directly compare a 15-year outcome against a 20-year or 25-year extended outcome by simply adjusting the tenure slider.
PPF vs NPS — a quick comparison
PPF is the guaranteed, government-backed ballast in a retirement portfolio, offering a fixed, government-set rate with zero market risk and complete tax exemption at every stage. NPS is the higher-growth, market-linked engine, offering an additional ₹50,000 tax deduction beyond the standard 80C limit, but with the trade-off of market risk during accumulation and a mandatory annuity purchase at retirement. Many financial planners suggest funding PPF up to its annual ₹1.5 lakh cap first for the guaranteed, fully tax-free component of a retirement plan, then directing any additional retirement savings toward NPS or equity mutual funds for higher growth potential.
PPF vs FD for long-term savings
Compared to a Fixed Deposit, PPF offers a meaningfully better tax treatment — FD interest is fully taxable at your income slab rate, while PPF interest is entirely tax-free. However, an FD offers far greater flexibility, with tenures as short as 7 days and easy premature withdrawal, while PPF locks your money in for a mandatory 15 years with only limited partial withdrawal options. For genuinely long-term goals — retirement, a child’s higher education 15+ years away — PPF’s tax-free compounding tends to outperform an equivalent FD after accounting for tax, but for shorter or uncertain time horizons, an FD’s flexibility is usually more valuable.
Who should use this calculator
Anyone opening a new PPF account, extending an existing one past the initial 15 years, or simply wanting to know what their yearly deposits will be worth at maturity will find this calculator directly useful for retirement and long-term goal planning. It’s also useful for deciding how much of your available 80C limit to allocate toward PPF versus other 80C-eligible instruments like ELSS mutual funds or life insurance premiums, by comparing PPF’s guaranteed outcome against the higher but variable potential returns of market-linked alternatives.
Frequently asked questions
Can I open more than one PPF account? No — an individual can hold only one PPF account in their own name (a separate account can be opened for a minor child, subject to combined contribution limits across both accounts).
What happens if I miss a yearly PPF deposit? Your account becomes inactive (though it continues earning interest on the existing balance) and can be reactivated by paying a small penalty along with the minimum required deposit for each missed year.
Is the PPF interest rate fixed for the full 15-year tenure? No — the rate is reset quarterly by the government based on prevailing conditions, and applies to the entire outstanding balance for that quarter, not just new deposits. The calculator lets you use the current rate as your best available assumption for the full period.
Can I withdraw my entire PPF balance after exactly 15 years? Yes — at the end of the initial 15-year tenure, you can withdraw the entire maturity amount tax-free and close the account, without any obligation to extend it further.
Try it now
Open the PPF Calculator on AliGreat.com and see your 15-year (or longer) maturity value in seconds — free, accurate, and fully transparent about the formula used.